Price reduction or seller credit? Let’s make those dollars work as hard as possible.
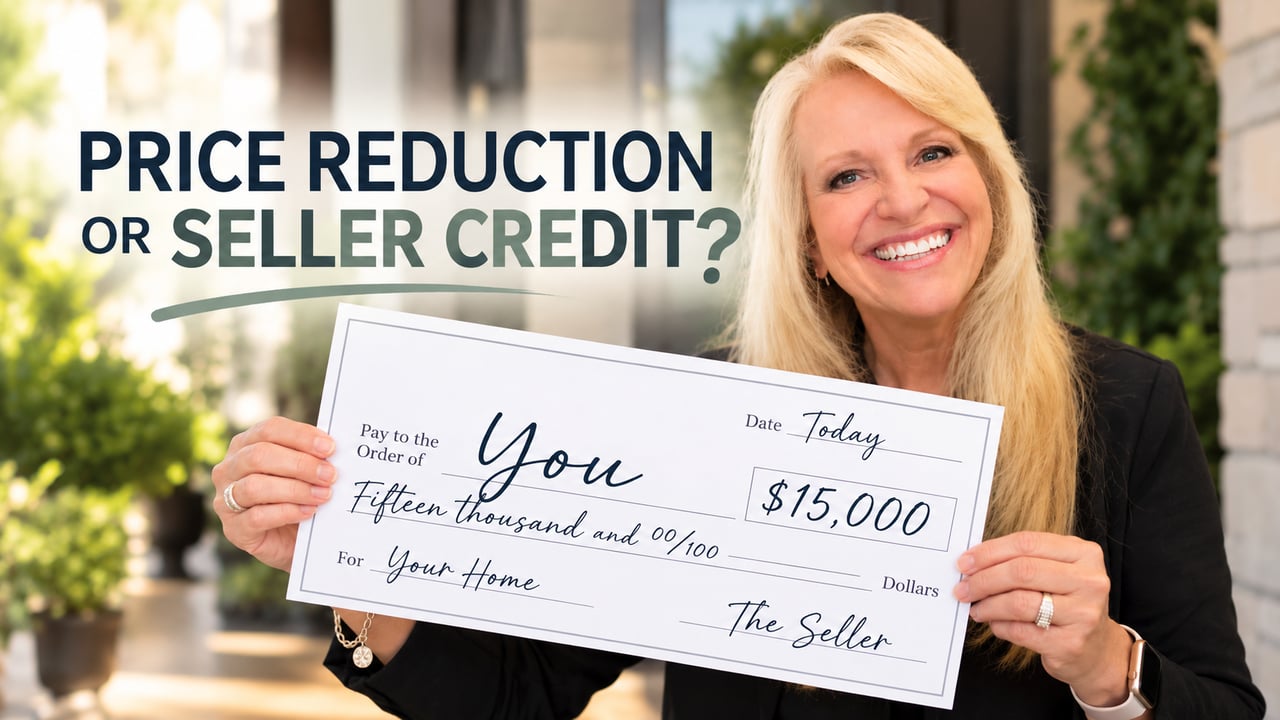
Imagine the seller says: “I’m willing to give you $15,000.”
Okay—that gets my attention. 😊 Now what?
Do you ask them to reduce the purchase price by $15,000? Do you use those dollars toward eligible closing costs and prepaids? Could some of it be used for a temporary buydown? Would a permanent rate buydown make more sense?
There isn’t one automatic answer.
But before you simply take the money off the top of the purchase price, let’s do the math and explore what those differences will mean to you.
Because those same seller dollars can produce very different results depending on where we put them.
A Lower Price Sounds Like the Obvious Win
And sometimes it is. Everybody likes getting a better price on a house. If the seller is willing to reduce the purchase price, there is absolutely value in that.
But here is the part buyers are sometimes surprised by:
A fairly significant price reduction may not change the monthly mortgage payment nearly as much as you expect.
Let’s use a simple illustration.
- Purchase price: $600,000
- 5% down payment
- Loan amount: $570,000
- At 7% on a 30-year fixed loan, principal and interest is approximately $3,792 per month
Now let’s say the seller agrees to reduce the purchase price by $15,000, bringing it down to $585,000.
- With the same 5% down structure, the new loan amount would be approximately $555,750, and principal and interest would be about $3,697 per month.
- So that $15,000 reduction in the purchase price saves roughly $95 per month in principal and interest.
Helpful? Absolutely.
But now let’s see what else those same seller dollars might do.
These examples are for illustration only. Actual rates, pricing, down payments, loan amounts, allowable seller contributions and costs will vary.
What If the Seller Helps With Your Closing Costs Instead?
Buying a home requires more than the down payment.
There are closing costs and prepaids. Depending on the transaction, the “prepaids” include property taxes, homeowners insurance, HOA-related amounts and other eligible items (timing items) that have to be funded at closing.
That money has to come from somewhere.
So if a seller credit can cover allowable closing costs and prepaids, the buyer may be able to keep thousands of dollars that otherwise would have left their bank account at closing to cover these items.
That can be a very different kind of win.
Maybe those dollars remain in savings … Maybe they become the emergency fund … Maybe they help with moving, furniture or the inevitable first few things you discover after getting the keys.
A lower price helps over time. A seller credit may help your cash position immediately.
And depending on the buyer, that can matter enormously.
Then There’s the Rate
This is where mortgage strategy gets really fun for me.
A seller credit may also be available, subject to loan-program requirements, to help fund an allowable temporary or permanent buydown. We’ll get to “temporary buydowns” in a minute.
A permanent buydown means paying “prepaid interest,” which is called a discount point or points, paid upfront at closing to obtain a lower interest rate for the life of the loan. One discount point equals 1% of the loan amount. For example, one point on a $570,000 loan would cost $5,700.
In other words, instead of simply reducing the purchase price, some of the seller’s dollars may be used to help buy the rate down and lower the buyer’s monthly principal-and-interest payment for as long as they keep that loan.
Let’s stay with our same example:
- Purchase price: $600,000
- 5% down payment
- Loan amount: $570,000
- At a 7% note rate, principal and interest is about $3,792 per month
- If market pricing allowed a permanent buydown from 7% to 6.625%, principal and interest would be approximately $3,650 per month
- That is about $142 per month in payment difference
Compare that with roughly $95 per month from reducing the purchase price by $15,000.
Now we’re asking a much better question than:
“Can we get the seller to lower the price?”
We’re asking:
“Where will the seller’s money benefit THIS buyer the most?”
The cost of a permanent buydown changes with market pricing, so a particular seller credit will not always purchase a particular rate reduction. That is exactly why we run the numbers rather than guess.
And Sometimes a Temporary Buydown Wins the Day
I just closed a loan where we had this very conversation.
A temporary buydown is a way to reduce the borrower’s monthly payment for the first one or more years of the loan. Funds are set aside upfront in a buydown account and used to subsidize part of the payment during that time. The actual note rate stays the same.
The buyer had several options available, and we went through them together. We looked at the cash, the payment, the financing and what would create the most meaningful benefit for him.
He chose a 2-1 temporary buydown.
Here is how a 2-1 buydown works in a simplified example using our same $600,000 purchase price, 5% down and $570,000 loan amount:
- Year 1: payment calculated as though the rate were 5% — about $3,060 P&I, a savings of roughly $732 per month
- Year 2: payment calculated as though the rate were 6% — about $3,417 P&I, a savings of roughly $375 per month
- Year 3 and beyond: full payment based on the actual 7% note rate — about $3,792 P&I
Now THAT gets interesting.
The note rate itself remains 7%; the buydown funds are simply subsidizing part of the payment during those first two years. Temporary buydowns also have specific program and funding requirements, so again, we have to structure them correctly.
But this is exactly why I never want to automatically assume a price reduction is the biggest win.
Same Seller. Same Negotiation. Very Different Results.
Think about the possibilities.
One buyer may desperately need to preserve cash at closing. Another may have plenty of cash but wants the lowest long-term payment possible. Another may love the idea of significantly lower payments during the first couple of years while they settle into the new home. And another buyer may absolutely prefer the lower purchase price.
All of those answers can be right.
The right answer depends on the buyer.
That’s why when a seller is willing to negotiate, I love getting involved before the terms are finalized.
Let’s run the scenarios.
- Price reduction.
- Closing costs.
- Prepaids.
- Temporary buydown.
- Permanent buydown.
- Maybe even a combination, depending on what is allowable and what the buyer actually needs.
Then you and your REALTOR® can negotiate with a strategy instead of simply asking for the most obvious concession—a lower price.
Let’s Make the Seller’s Dollars Work Harder
In a transaction where the seller is willing to give something up, imagine they have essentially handed you a check.
What should we do with it?
My answer is: Let’s not decide until we run the numbers.
Because sometimes taking money off the purchase price is the right answer.
But very often—especially when cash to close or monthly payment is the bigger concern—using an allowable seller credit strategically can create a much more noticeable benefit.
And I love helping buyers peel all of this back.
Show me the offer. Show me what the seller is willing to do. Tell me what matters most to you.
Then let’s look at the options and decide where those dollars can work the hardest.
Before you negotiate the concession, let’s give every seller dollar the right job. 🏡💚
— SE